Best Finance Startups & Tools

Recently Listed

57 launches
Sort
I

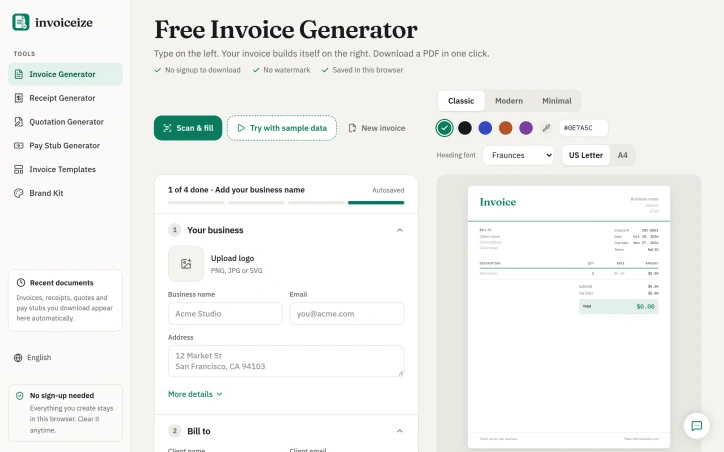
Freelancers and small business owners often struggle with the administrative burden of billing, particularly when facing bloated invoicing software with steep learning curves and subscription fees. Invoiceize tackles this friction head-on by delivering a straightforward, free invoice generator that works entirely in the browser without requiring registration or account creation. The product's core appeal lies in its simplicity and lack of friction. Users input business details, client information, and line items on the left side of the interface while watching a formatted invoice assemble in real time on the right. This live preview model eliminates guesswork about layout and ensures accuracy before generation. Once complete, users download a clean PDF with no watermarks or promotional branding—a notable differentiator from many freemium tools. Invoiceize covers the full invoicing workflow with practical features. The generator automatically calculates line-item totals, taxes, and discounts as users type. It supports 23 currencies, recognizing that freelancers increasingly work across borders. Three design templates (Classic, Modern, Minimal) accommodate different professional aesthetics, while customizable fonts, colors, and logo uploads allow branding without design skills. The interface even supports bulk data entry through copy-paste from spreadsheet applications. Beyond invoices, the tool extends to receipts—automatically generating one for paid invoices with a single click. This breadth matters for businesses managing both outgoing invoices and incoming payments in one workflow. An optional AI-assisted document scanner offers convenience for users with existing paperwork to formalize. The tool also provides granular customization: every label on the invoice can be renamed, payment terms defaulted, and custom fields added for POs or tax IDs. Local browser storage means drafts persist without cloud dependencies or vendor lock-in concerns. The business model is refreshingly transparent. Invoiceize remains entirely free with zero signup barriers. The only trade-off offered is optional: a small "Made with invoiceize.com" credit in the footer, which users can choose to include or remove. There is no mention of paid tiers, API access, or premium features. For freelancers drowning in invoicing complexity or small businesses seeking a no-nonsense, cost-free solution, Invoiceize delivers legitimately useful functionality. Its strength lies not in innovation but in execution—removing every unnecessary obstacle between a blank form and a professional invoice ready to send.
Invoicing-tools
B
BitSun

Freelancers and small business owners often struggle with the administrative burden of billing, particularly when facing bloated invoicing software with steep learning curves and subscription fees. Invoiceize tackles this friction head-on by delivering a straightforward, free invoice generator that works entirely in the browser without requiring registration or account creation. The product's core appeal lies in its simplicity and lack of friction. Users input business details, client information, and line items on the left side of the interface while watching a formatted invoice assemble in real time on the right. This live preview model eliminates guesswork about layout and ensures accuracy before generation. Once complete, users download a clean PDF with no watermarks or promotional branding—a notable differentiator from many freemium tools. Invoiceize covers the full invoicing workflow with practical features. The generator automatically calculates line-item totals, taxes, and discounts as users type. It supports 23 currencies, recognizing that freelancers increasingly work across borders. Three design templates (Classic, Modern, Minimal) accommodate different professional aesthetics, while customizable fonts, colors, and logo uploads allow branding without design skills. The interface even supports bulk data entry through copy-paste from spreadsheet applications. Beyond invoices, the tool extends to receipts—automatically generating one for paid invoices with a single click. This breadth matters for businesses managing both outgoing invoices and incoming payments in one workflow. An optional AI-assisted document scanner offers convenience for users with existing paperwork to formalize. The tool also provides granular customization: every label on the invoice can be renamed, payment terms defaulted, and custom fields added for POs or tax IDs. Local browser storage means drafts persist without cloud dependencies or vendor lock-in concerns. The business model is refreshingly transparent. Invoiceize remains entirely free with zero signup barriers. The only trade-off offered is optional: a small "Made with invoiceize.com" credit in the footer, which users can choose to include or remove. There is no mention of paid tiers, API access, or premium features. For freelancers drowning in invoicing complexity or small businesses seeking a no-nonsense, cost-free solution, Invoiceize delivers legitimately useful functionality. Its strength lies not in innovation but in execution—removing every unnecessary obstacle between a blank form and a professional invoice ready to send.

Invoiceize preview
I

Key features

  • Live Invoice Preview: Input business details on the left while a formatted invoice assembles in real time on the right.
  • Multi-Currency Support: Supports 23 currencies for freelancers and businesses working across borders.
See full listing
Tapetide

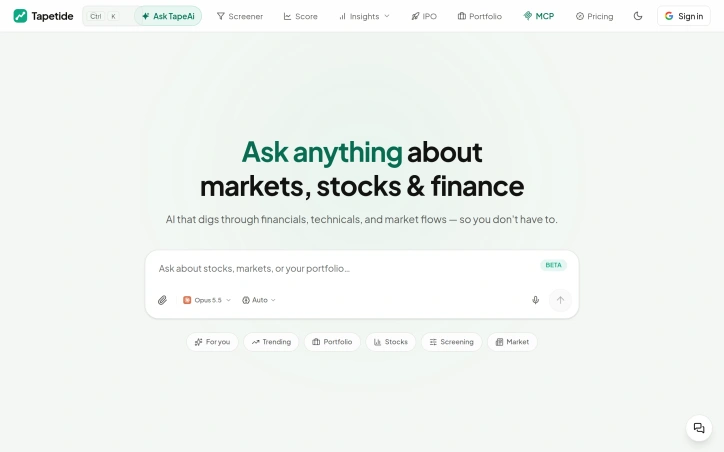
Indian stock research traditionally demands toggling between multiple databases and websites to gather prices, financials, shareholding patterns, and market data. Tapetide consolidates this fragmented landscape into a single AI-powered interface designed for retail and professional investors analyzing equities on the National Stock Exchange and Bombay Stock Exchange. The product's core innovation lies in its natural language approach. Instead of navigating traditional screens and search filters, users ask questions in plain English: "compare HDFC Bank and ICICI Bank on ROE and valuation" or similar queries. The system retrieves corresponding financial metrics, parses supporting documents, and presents results with charts and tables. This conversational methodology appeals to investors who lack the time or inclination to master specialized research tools. The platform covers more than 8,000 listed companies with historical pricing data extending back to 2000 and financial statements spanning 12 years. Beyond basic metrics, Tapetide includes shareholding patterns, technical indicators, analyst ratings, and parsed corporate filings including annual reports and earnings call transcripts. A stock screener offering 326 different ratios and live technical signals accommodates more sophisticated screening requirements. Market-level dashboards track foreign institutional flows, initial public offerings, block deals, and mutual fund positioning. Tapetide extends beyond its web interface through an MCP server that integrates with Claude, ChatGPT, Cursor, and other AI tools. Developers and power users can access 55 market data tools directly from compatible MCP clients, removing the need for separate account management across platforms. This integration positions the product within the broader AI-native tool ecosystem rather than treating AI as an afterthought. The business model emphasizes accessibility. A free tier unlocks the stock screener, limited MCP calls (50 daily), and foundational market dashboards. Paid subscriptions begin at 299 rupees monthly with a week-long trial period. This pricing structure maintains low barriers to entry for cost-conscious investors in India while supporting a sustainable business model. Tapetide addresses a genuine friction point in Indian stock research by reducing platform fragmentation. The AI-first execution distinguishes it from traditional research portals that merely aggregate data, positioning the product as a genuine productivity tool rather than an incremental improvement to existing workflows.
Indian stock research traditionally demands toggling between multiple databases and websites to gather prices, financials, shareholding patterns, and market data. Tapetide consolidates this fragmented landscape into a single AI-powered interface designed for retail and professional investors analyzing equities on the National Stock Exchange and Bombay Stock Exchange. The product's core innovation lies in its natural language approach. Instead of navigating traditional screens and search filters, users ask questions in plain English: "compare HDFC Bank and ICICI Bank on ROE and valuation" or similar queries. The system retrieves corresponding financial metrics, parses supporting documents, and presents results with charts and tables. This conversational methodology appeals to investors who lack the time or inclination to master specialized research tools. The platform covers more than 8,000 listed companies with historical pricing data extending back to 2000 and financial statements spanning 12 years. Beyond basic metrics, Tapetide includes shareholding patterns, technical indicators, analyst ratings, and parsed corporate filings including annual reports and earnings call transcripts. A stock screener offering 326 different ratios and live technical signals accommodates more sophisticated screening requirements. Market-level dashboards track foreign institutional flows, initial public offerings, block deals, and mutual fund positioning. Tapetide extends beyond its web interface through an MCP server that integrates with Claude, ChatGPT, Cursor, and other AI tools. Developers and power users can access 55 market data tools directly from compatible MCP clients, removing the need for separate account management across platforms. This integration positions the product within the broader AI-native tool ecosystem rather than treating AI as an afterthought. The business model emphasizes accessibility. A free tier unlocks the stock screener, limited MCP calls (50 daily), and foundational market dashboards. Paid subscriptions begin at 299 rupees monthly with a week-long trial period. This pricing structure maintains low barriers to entry for cost-conscious investors in India while supporting a sustainable business model. Tapetide addresses a genuine friction point in Indian stock research by reducing platform fragmentation. The AI-first execution distinguishes it from traditional research portals that merely aggregate data, positioning the product as a genuine productivity tool rather than an incremental improvement to existing workflows.

Tapetide preview

Key features

  • Natural Language Queries: Ask questions in plain English about stock analysis instead of navigating complex interfaces.
  • Consolidated Research Hub: Integrates prices, financials, shareholding patterns, and market data in one platform.
See full listing
Quote & Estimate Maker

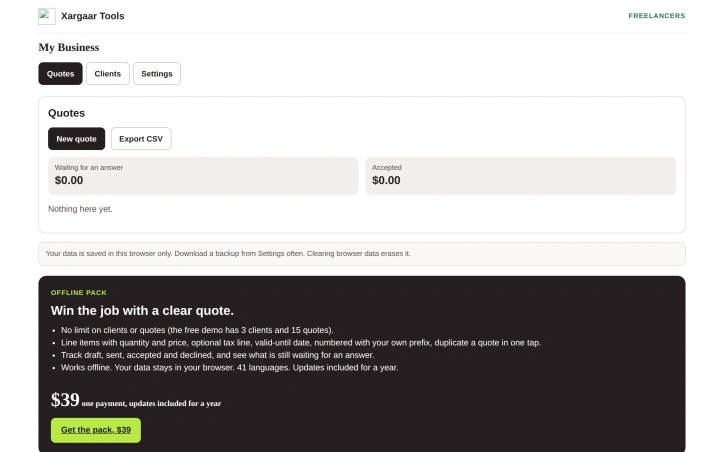
Quote & Estimate Maker is a browser-based tool for freelancers and small service businesses who need to send professional quotes without setting up invoicing software. It creates numbered, printable quotes with line items, quantities, prices, and optional tax, and quote numbers are assigned automatically so they stay unique. Each quote can carry a valid-until date so old prices do not hang around. Follow-up stays visible: the user marks each quote as sent, accepted, or declined, so it is always clear which quotes are still waiting for an answer. An existing quote can be duplicated to start a new one for the same or a different client. The tool runs entirely in the browser with no account and no server, works in 41 languages, and stores data on the user's own device, with backups available for download.
Invoicing-tools
T
Tyr Xargaar

Quote & Estimate Maker is a browser-based tool for freelancers and small service businesses who need to send professional quotes without setting up invoicing software. It creates numbered, printable quotes with line items, quantities, prices, and optional tax, and quote numbers are assigned automatically so they stay unique. Each quote can carry a valid-until date so old prices do not hang around. Follow-up stays visible: the user marks each quote as sent, accepted, or declined, so it is always clear which quotes are still waiting for an answer. An existing quote can be duplicated to start a new one for the same or a different client. The tool runs entirely in the browser with no account and no server, works in 41 languages, and stores data on the user's own device, with backups available for download.

Quote & Estimate Maker preview

Key features

  • Professional Quote Generation: Creates numbered, printable quotes with line items, customizable pricing, and tax calculations.
  • Lifecycle Tracking: Monitors quote status through draft, sent, accepted, and declined states.
See full listing
BaseAcross

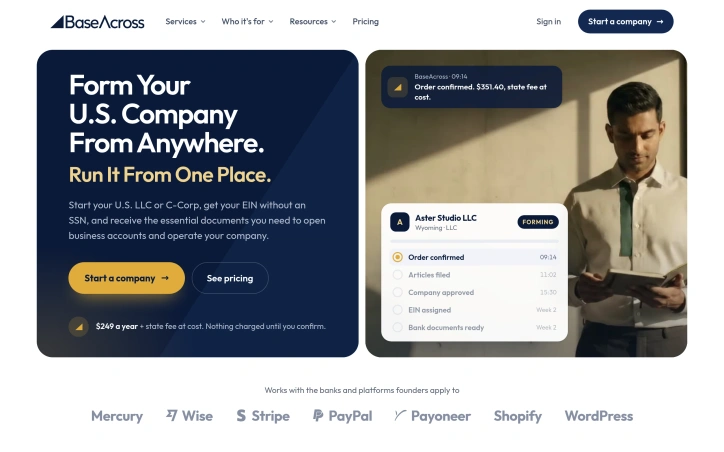
Forming a US company as a foreign entrepreneur has historically been a friction-filled process. BaseAcross eliminates that friction by handling corporate formation and ongoing compliance entirely for non-resident founders who lack a US Social Security Number or physical address. The product targets a specific and underserved market: international founders who want to establish legitimacy, open US bank accounts, and accept payments via Stripe without navigating Byzantine bureaucracy or hiring expensive lawyers. The solution encompasses the entire lifecycle—from LLC or C-Corp incorporation in Wyoming or Delaware through annual compliance filings, compliance deadline tracking, and essential documentation for banking applications. What distinguishes BaseAcross is the comprehensiveness of its integrated offering. Beyond formation, the platform handles EIN assignment without requiring an SSN, a critical advantage for non-resident founders. It generates the specific documents that US banks demand, maintains compliance calendars with cost estimates surfaced well in advance, and connects users to startup credit programs from Google Cloud, AWS, and Microsoft. The platform also extends into adjacent needs: it provisions a US business phone number, sets up professional email and business domains, provides bookkeeping with automated transaction categorization, and offers managed WordPress or Shopify hosting. The user experience is designed for transparency. The timeline is explicit: same-day filing after confirmation, EIN assignment within one to two weeks, and bank-ready documents shortly after. Users see the full order and cost before paying, with the platform handling communication with state filing agencies throughout. Pricing is straightforward: $249 annually plus state fees at cost. The example shown—$351.40 total for Wyoming incorporation—reflects actual filing costs passed through without markup. Certain features like the US phone number and domain are free for the first three months, then included in the ongoing "Operate" plan. Annual compliance obligations like state reports carry transparent pricing shown in advance. The platform integrates deeply with financial infrastructure founders actually use: Mercury, Stripe, PayPal, Shopify, and others are embedded throughout the product. This reflects BaseAcross's understanding of what founders need downstream and builds the company formation experience around those requirements. For non-resident founders, particularly those bootstrapping or early-stage, BaseAcross removes a genuine barrier to incorporating in the US and accessing US financial rails without that incorporation requiring a US presence or identity number.
Startup-incorporation
N
Nishesh Patel

Forming a US company as a foreign entrepreneur has historically been a friction-filled process. BaseAcross eliminates that friction by handling corporate formation and ongoing compliance entirely for non-resident founders who lack a US Social Security Number or physical address. The product targets a specific and underserved market: international founders who want to establish legitimacy, open US bank accounts, and accept payments via Stripe without navigating Byzantine bureaucracy or hiring expensive lawyers. The solution encompasses the entire lifecycle—from LLC or C-Corp incorporation in Wyoming or Delaware through annual compliance filings, compliance deadline tracking, and essential documentation for banking applications. What distinguishes BaseAcross is the comprehensiveness of its integrated offering. Beyond formation, the platform handles EIN assignment without requiring an SSN, a critical advantage for non-resident founders. It generates the specific documents that US banks demand, maintains compliance calendars with cost estimates surfaced well in advance, and connects users to startup credit programs from Google Cloud, AWS, and Microsoft. The platform also extends into adjacent needs: it provisions a US business phone number, sets up professional email and business domains, provides bookkeeping with automated transaction categorization, and offers managed WordPress or Shopify hosting. The user experience is designed for transparency. The timeline is explicit: same-day filing after confirmation, EIN assignment within one to two weeks, and bank-ready documents shortly after. Users see the full order and cost before paying, with the platform handling communication with state filing agencies throughout. Pricing is straightforward: $249 annually plus state fees at cost. The example shown—$351.40 total for Wyoming incorporation—reflects actual filing costs passed through without markup. Certain features like the US phone number and domain are free for the first three months, then included in the ongoing "Operate" plan. Annual compliance obligations like state reports carry transparent pricing shown in advance. The platform integrates deeply with financial infrastructure founders actually use: Mercury, Stripe, PayPal, Shopify, and others are embedded throughout the product. This reflects BaseAcross's understanding of what founders need downstream and builds the company formation experience around those requirements. For non-resident founders, particularly those bootstrapping or early-stage, BaseAcross removes a genuine barrier to incorporating in the US and accessing US financial rails without that incorporation requiring a US presence or identity number.

BaseAcross preview

Key features

  • Corporate Formation: Handles LLC or C-Corp incorporation in Wyoming or Delaware for non-resident founders
  • EIN Assignment Without SSN: Enables EIN assignment without requiring a US Social Security Number
See full listing
Recon Smart by Finora Solutions

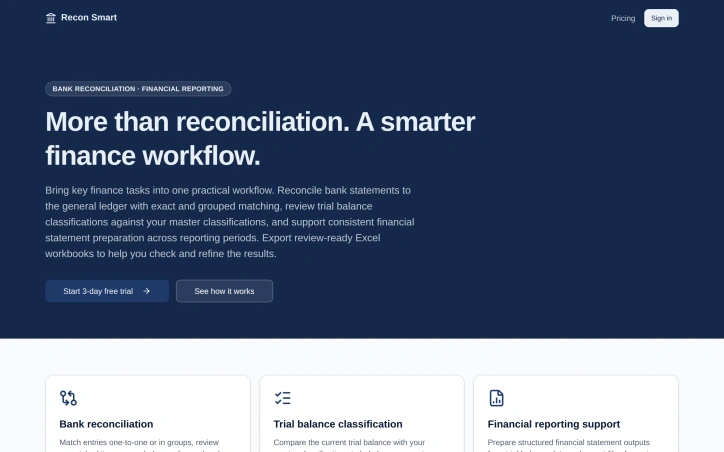
Finance teams spend substantial time on reconciliation work, transaction matching, and financial reporting—tasks that demand accuracy but often consume disproportionate resources. Recon Smart tackles this challenge by consolidating multiple accounting workflows into a single platform. The product targets accountants and finance professionals who handle routine reconciliation tasks. Rather than jumping between different tools for bank reconciliation, trial balance review, and statement preparation, users manage these core functions from one interface. The founder built this solution from personal experience in accounting operations, addressing the frustration of repetitive manual processes that detract from higher-value analysis work. What distinguishes Recon Smart is its integration of transaction matching intelligence into the reconciliation workflow. The platform suggests matches between bank transactions and recorded entries, reducing the manual effort required to identify discrepancies. This capability pairs with trial balance classification, allowing finance teams to organize accounts efficiently, and extends through financial statement preparation and reporting. The feature set covers the full cycle of monthly close and financial management work that teams typically fragment across spreadsheets and specialized tools. Development draws from practical accounting workflows. The founder validated Recon Smart using real financial data, demonstrating the interface and features address genuine operational challenges rather than theoretical process improvements. This grounding reduces the typical startup risk of building tools that look elegant but struggle with messy, real-world data. The positioning emphasizes efficiency gains and time savings rather than fundamental transformation. The founder frames the solution as a way to handle necessary financial work more quickly, freeing professionals to focus on analysis and strategy. That's a realistic promise in an industry where many new tools oversell their impact. The consolidation alone—reducing tool switching and duplicate data entry—delivers tangible benefits even before considering the matching intelligence features. One constraint worth noting: the publicly available information contains no mention of pricing, deployment options, or integration capabilities. For finance teams considering adoption, these details matter significantly and remain undisclosed. Similarly, the extent to which Recon Smart handles complex scenarios—multi-currency transactions, intercompany reconciliations, or regulatory-specific reporting—isn't addressed in available materials. Recon Smart addresses a clear operational pain point in accounting departments with a product built on authentic domain expertise. For teams handling manual reconciliation at scale, the consolidated workflow and matching intelligence offer legitimate efficiency improvements worth evaluating.
Accounting-software
F
Finora Solutions

Finance teams spend substantial time on reconciliation work, transaction matching, and financial reporting—tasks that demand accuracy but often consume disproportionate resources. Recon Smart tackles this challenge by consolidating multiple accounting workflows into a single platform. The product targets accountants and finance professionals who handle routine reconciliation tasks. Rather than jumping between different tools for bank reconciliation, trial balance review, and statement preparation, users manage these core functions from one interface. The founder built this solution from personal experience in accounting operations, addressing the frustration of repetitive manual processes that detract from higher-value analysis work. What distinguishes Recon Smart is its integration of transaction matching intelligence into the reconciliation workflow. The platform suggests matches between bank transactions and recorded entries, reducing the manual effort required to identify discrepancies. This capability pairs with trial balance classification, allowing finance teams to organize accounts efficiently, and extends through financial statement preparation and reporting. The feature set covers the full cycle of monthly close and financial management work that teams typically fragment across spreadsheets and specialized tools. Development draws from practical accounting workflows. The founder validated Recon Smart using real financial data, demonstrating the interface and features address genuine operational challenges rather than theoretical process improvements. This grounding reduces the typical startup risk of building tools that look elegant but struggle with messy, real-world data. The positioning emphasizes efficiency gains and time savings rather than fundamental transformation. The founder frames the solution as a way to handle necessary financial work more quickly, freeing professionals to focus on analysis and strategy. That's a realistic promise in an industry where many new tools oversell their impact. The consolidation alone—reducing tool switching and duplicate data entry—delivers tangible benefits even before considering the matching intelligence features. One constraint worth noting: the publicly available information contains no mention of pricing, deployment options, or integration capabilities. For finance teams considering adoption, these details matter significantly and remain undisclosed. Similarly, the extent to which Recon Smart handles complex scenarios—multi-currency transactions, intercompany reconciliations, or regulatory-specific reporting—isn't addressed in available materials. Recon Smart addresses a clear operational pain point in accounting departments with a product built on authentic domain expertise. For teams handling manual reconciliation at scale, the consolidated workflow and matching intelligence offer legitimate efficiency improvements worth evaluating.

Recon Smart by Finora Solutions preview

Key features

  • Transaction Matching Intelligence: Suggests matches between bank transactions and recorded entries to reduce manual reconciliation effort
  • Trial Balance Classification: Organizes accounts efficiently within the reconciliation workflow
See full listing
Inventoryaccounting

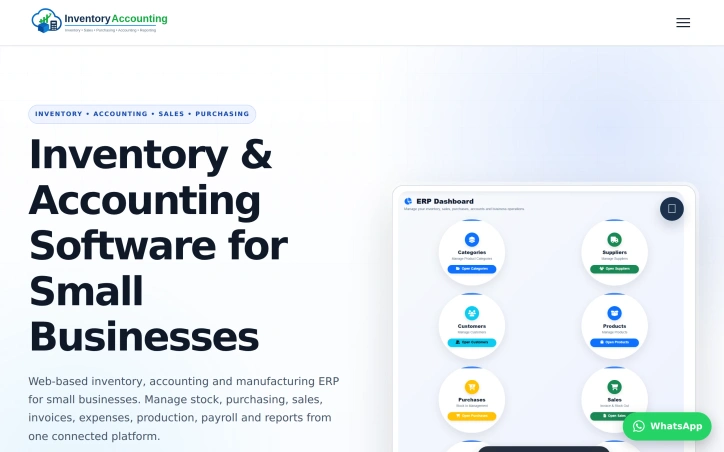
Disconnected spreadsheets and siloed point solutions plague small business operations, particularly for companies managing inventory alongside financial records. Inventory Accounting addresses this fragmentation by consolidating stock management, purchasing, sales, invoicing, accounting, and manufacturing workflows into a single web-based platform designed specifically for small to mid-sized businesses. The platform targets companies managing physical goods—manufacturers relying on bill-of-materials workflows, wholesalers coordinating suppliers and customer sales, retailers tracking products and transactions, and warehouses monitoring stock levels and movement. Multi-company operators gain the additional benefit of maintaining separate operations within one system while controlling user access through role-based permissions. What distinguishes this offering is its emphasis on genuine operational integration rather than bolted-together modules. The connection between stock activity and financial records flows throughout the system: inventory movements automatically impact accounting records, customer invoices remain tethered to stock deductions, and manufacturing processes chain raw materials through production to finished goods. Rather than asking users to manually reconcile inventory spreadsheets against accounting ledgers, the platform enforces consistency at the transaction level. The feature set covers the operational cycle comprehensively. Stock visibility includes real-time quantity reporting and low-stock alerts. Sales workflows connect customer activity, product selection, and invoice generation. Purchasing tracks suppliers, incoming stock, and payment obligations. The manufacturing module handles bill-of-materials definitions with quantities and waste allowances. Accounting delivers traditional ledger and reporting capabilities including profit-and-loss statements, balance sheets, and cash-flow workflows. Role-based access ensures appropriate visibility across departments without exposing sensitive financial data to line staff. The product positions itself against enterprise ERP platforms by eliminating unnecessary complexity while delivering genuine integration. The company showcases real implementation screens from working deployments rather than relying on mockups or heavily scripted demonstrations, suggesting confidence in practical usability. One notable gap: the website materials omit explicit pricing information, forcing prospective customers to book demos to understand cost structure. For businesses evaluating multiple solutions, this opacity represents a friction point in the evaluation process. Inventory Accounting fills a legitimate gap for growing businesses drowning in spreadsheet complexity but not yet ready for enterprise software. Its success depends on execution—whether the integrations work smoothly in real business environments and whether customers actually reduce manual work rather than simply replacing one system with another.
Accounting-software
S
Salman Nasir

Disconnected spreadsheets and siloed point solutions plague small business operations, particularly for companies managing inventory alongside financial records. Inventory Accounting addresses this fragmentation by consolidating stock management, purchasing, sales, invoicing, accounting, and manufacturing workflows into a single web-based platform designed specifically for small to mid-sized businesses. The platform targets companies managing physical goods—manufacturers relying on bill-of-materials workflows, wholesalers coordinating suppliers and customer sales, retailers tracking products and transactions, and warehouses monitoring stock levels and movement. Multi-company operators gain the additional benefit of maintaining separate operations within one system while controlling user access through role-based permissions. What distinguishes this offering is its emphasis on genuine operational integration rather than bolted-together modules. The connection between stock activity and financial records flows throughout the system: inventory movements automatically impact accounting records, customer invoices remain tethered to stock deductions, and manufacturing processes chain raw materials through production to finished goods. Rather than asking users to manually reconcile inventory spreadsheets against accounting ledgers, the platform enforces consistency at the transaction level. The feature set covers the operational cycle comprehensively. Stock visibility includes real-time quantity reporting and low-stock alerts. Sales workflows connect customer activity, product selection, and invoice generation. Purchasing tracks suppliers, incoming stock, and payment obligations. The manufacturing module handles bill-of-materials definitions with quantities and waste allowances. Accounting delivers traditional ledger and reporting capabilities including profit-and-loss statements, balance sheets, and cash-flow workflows. Role-based access ensures appropriate visibility across departments without exposing sensitive financial data to line staff. The product positions itself against enterprise ERP platforms by eliminating unnecessary complexity while delivering genuine integration. The company showcases real implementation screens from working deployments rather than relying on mockups or heavily scripted demonstrations, suggesting confidence in practical usability. One notable gap: the website materials omit explicit pricing information, forcing prospective customers to book demos to understand cost structure. For businesses evaluating multiple solutions, this opacity represents a friction point in the evaluation process. Inventory Accounting fills a legitimate gap for growing businesses drowning in spreadsheet complexity but not yet ready for enterprise software. Its success depends on execution—whether the integrations work smoothly in real business environments and whether customers actually reduce manual work rather than simply replacing one system with another.

Inventoryaccounting preview

Key features

  • Unified Platform: Consolidates inventory, purchasing, sales, invoicing, accounting, and manufacturing into a single web-based system designed for small to mid-sized businesses.
  • Real-Time Stock Visibility: Provides real-time quantity reporting and automatic low-stock alerts to prevent stockouts.
See full listing
C

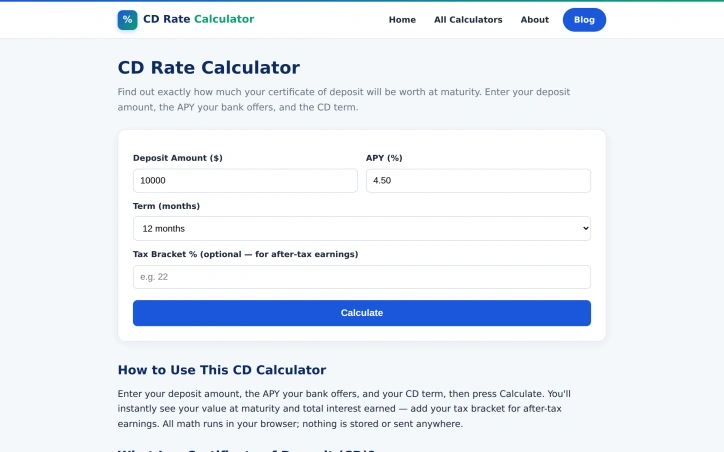
Anyone frustrated by the opaque process of comparing certificate of deposit rates across institutions will recognize the immediate appeal of this calculator. The tool addresses a genuine friction point: banks advertise CD rates inconsistently, and manually calculating compound interest across multiple terms and deposit amounts is tedious enough that many people skip the comparison altogether. The product positions itself as a solution for savers trying to maximize returns on money they don't plan to touch for months or years. That audience spans from risk-averse investors seeking alternatives to volatile markets to people parking emergency funds while still earning better yields than traditional savings accounts. What distinguishes this offering is its deliberate simplicity and transparency. The tool runs entirely in the browser, eliminating any data collection or transmission to servers. This design choice doubles as both a privacy feature and a speed advantage—users get instant calculations without waiting for network requests. The calculator accepts standard inputs: deposit amount, annual percentage yield, and term length ranging from three months to five years. An optional tax bracket field lets users see after-tax earnings, acknowledging that interest income carries tax implications many calculators ignore. The supporting content provides genuine educational value beyond the calculator itself. The site explains how CD interest compounds and why even small APY differences accumulate significantly on larger deposits. A reference table showing earnings across common deposit amounts and terms gives context for comparing real-world scenarios. The explanation of how CDs sit between savings accounts and investments frames the product for its intended audience. The underlying mathematics relies on the standard compound interest formula, which the site explicitly displays. This transparency around methodology builds credibility—users can verify calculations themselves. The business model appears to be free-to-use with no mention of premium tiers, subscriptions, or hidden monetization. The founder's motivation, stated as frustration with manual rate comparisons, aligns with the product's straightforward utility. One limitation worth noting: the tool assumes users already know their bank's offered APY and CD terms. It solves the earnings calculation problem but not the rate discovery problem—users still need to shop their bank's offerings separately. For savers serious about optimization, this represents only one step in the process rather than a complete solution. The calculator fills a genuine gap in the financial tools landscape by making CD earnings transparent and comparable without requiring a spreadsheet or calculator app.
Financial-planning
M
My magazine Myself

Anyone frustrated by the opaque process of comparing certificate of deposit rates across institutions will recognize the immediate appeal of this calculator. The tool addresses a genuine friction point: banks advertise CD rates inconsistently, and manually calculating compound interest across multiple terms and deposit amounts is tedious enough that many people skip the comparison altogether. The product positions itself as a solution for savers trying to maximize returns on money they don't plan to touch for months or years. That audience spans from risk-averse investors seeking alternatives to volatile markets to people parking emergency funds while still earning better yields than traditional savings accounts. What distinguishes this offering is its deliberate simplicity and transparency. The tool runs entirely in the browser, eliminating any data collection or transmission to servers. This design choice doubles as both a privacy feature and a speed advantage—users get instant calculations without waiting for network requests. The calculator accepts standard inputs: deposit amount, annual percentage yield, and term length ranging from three months to five years. An optional tax bracket field lets users see after-tax earnings, acknowledging that interest income carries tax implications many calculators ignore. The supporting content provides genuine educational value beyond the calculator itself. The site explains how CD interest compounds and why even small APY differences accumulate significantly on larger deposits. A reference table showing earnings across common deposit amounts and terms gives context for comparing real-world scenarios. The explanation of how CDs sit between savings accounts and investments frames the product for its intended audience. The underlying mathematics relies on the standard compound interest formula, which the site explicitly displays. This transparency around methodology builds credibility—users can verify calculations themselves. The business model appears to be free-to-use with no mention of premium tiers, subscriptions, or hidden monetization. The founder's motivation, stated as frustration with manual rate comparisons, aligns with the product's straightforward utility. One limitation worth noting: the tool assumes users already know their bank's offered APY and CD terms. It solves the earnings calculation problem but not the rate discovery problem—users still need to shop their bank's offerings separately. For savers serious about optimization, this represents only one step in the process rather than a complete solution. The calculator fills a genuine gap in the financial tools landscape by making CD earnings transparent and comparable without requiring a spreadsheet or calculator app.

CD Rate Calculator preview
C

Key features

  • Browser-Based Calculation: Runs entirely in your browser without sending data to servers
  • After-Tax Earnings: Optional tax bracket field shows actual after-tax returns
See full listing
True Take-Home

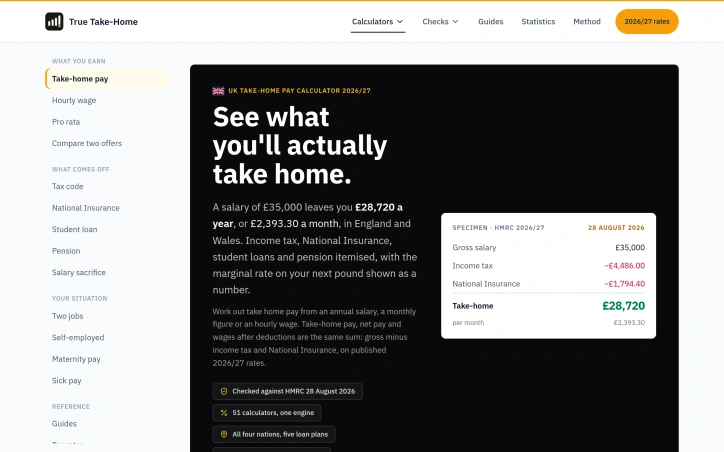
Many UK workers operate under a dangerous misconception: they guess their monthly take-home rather than calculate it. Income tax, National Insurance, student loans, and pensions interact in ways that confuse even financially literate employees. True Take-Home addresses this knowledge gap directly, providing a transparent breakdown of what actually lands in your bank account. The calculator handles genuine complexity across the UK's four tax systems. Scotland imposes different bands than England, Wales, and Northern Ireland, yet most payroll tools either oversimplify or ignore these distinctions. True Take-Home covers all regional variations through 51 distinct calculators, spanning everything from basic salaries to self-employment and contractor scenarios. Each calculator reflects the 2026/27 rates, verified against HMRC guidance from August 2026. What distinguishes this tool is its commitment to transparency without friction. The interface updates every figure instantly as you type, eliminating the friction of form submissions. The calculation runs entirely in your browser—no data travels to servers, addressing legitimate privacy concerns. There is no account creation, no email capture, no upsell. You input your salary, specify your region and tax code, and receive a complete breakdown showing not just take-home but also your marginal tax rate on the next pound earned and your effective tax rate overall. The presentation goes beyond raw numbers. The tool shows where each deduction goes—income tax, National Insurance, pensions—broken down across annual, monthly, weekly, and daily pay periods. Comparative context appears automatically, showing how your situation changed from the previous tax year and how close you are to the next rate threshold. For hourly workers, it calculates equivalent hourly take-home based on a standard working week. The trade-off inherent in such specificity is cognitive load. A calculator covering this much ground demands more input than simpler tools. Users must understand their tax code, decide whether to model their pension contribution, and select among loan repayment plans if applicable. This complexity mirrors the actual tax system rather than sanitizing it, which serves users seeking accuracy over simplicity. True Take-Home fills a genuine need for UK employees seeking to understand their actual disposable income. It makes the implicit mathematics of payroll explicit, removing the guesswork that leads workers to mistrust their paychecks.
Financial-planning
M
mir hadi

Many UK workers operate under a dangerous misconception: they guess their monthly take-home rather than calculate it. Income tax, National Insurance, student loans, and pensions interact in ways that confuse even financially literate employees. True Take-Home addresses this knowledge gap directly, providing a transparent breakdown of what actually lands in your bank account. The calculator handles genuine complexity across the UK's four tax systems. Scotland imposes different bands than England, Wales, and Northern Ireland, yet most payroll tools either oversimplify or ignore these distinctions. True Take-Home covers all regional variations through 51 distinct calculators, spanning everything from basic salaries to self-employment and contractor scenarios. Each calculator reflects the 2026/27 rates, verified against HMRC guidance from August 2026. What distinguishes this tool is its commitment to transparency without friction. The interface updates every figure instantly as you type, eliminating the friction of form submissions. The calculation runs entirely in your browser—no data travels to servers, addressing legitimate privacy concerns. There is no account creation, no email capture, no upsell. You input your salary, specify your region and tax code, and receive a complete breakdown showing not just take-home but also your marginal tax rate on the next pound earned and your effective tax rate overall. The presentation goes beyond raw numbers. The tool shows where each deduction goes—income tax, National Insurance, pensions—broken down across annual, monthly, weekly, and daily pay periods. Comparative context appears automatically, showing how your situation changed from the previous tax year and how close you are to the next rate threshold. For hourly workers, it calculates equivalent hourly take-home based on a standard working week. The trade-off inherent in such specificity is cognitive load. A calculator covering this much ground demands more input than simpler tools. Users must understand their tax code, decide whether to model their pension contribution, and select among loan repayment plans if applicable. This complexity mirrors the actual tax system rather than sanitizing it, which serves users seeking accuracy over simplicity. True Take-Home fills a genuine need for UK employees seeking to understand their actual disposable income. It makes the implicit mathematics of payroll explicit, removing the guesswork that leads workers to mistrust their paychecks.

True Take-Home preview

Key features

  • Regional Tax Coverage: Handles all four UK tax systems with 51 distinct calculators reflecting Scotland, England, Wales, and Northern Ireland variations
  • Real-Time Calculation: Updates every figure instantly as you type with no form submission required
See full listing
InvesTTable

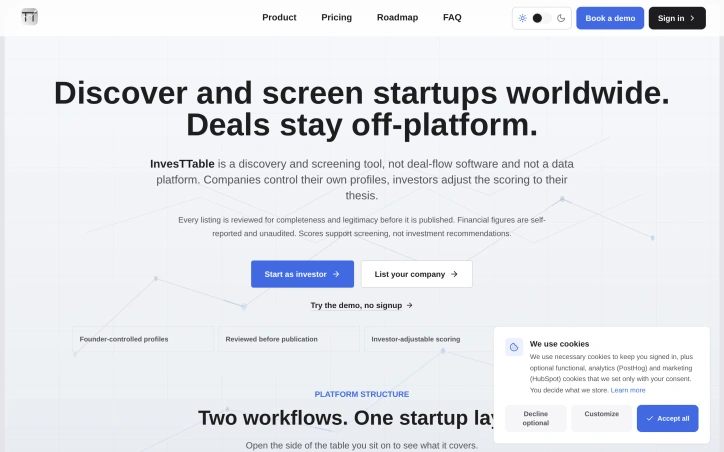
Matching investors with the right startups has long been a friction point for both sides. Investors filter through dozens of unqualified leads, while founders pursue funds with misaligned theses, wasting everyone's time. InvesTTable tackles this discovery problem head-on by creating a dual-sided screening platform where investors find scored, benchmarked startups and founders build discoverable profiles that reach aligned capital. The platform's architecture reflects deliberate design choices. Rather than positioning itself as deal-flow software or an investment platform, InvesTTable focuses narrowly on discovery and screening. Founders control their own profiles completely, deciding what to share down to full stealth mode. Every company listing undergoes review for completeness and legitimacy before publication, addressing a core trust issue in startup discovery. Investors receive structured data without gatekeeping; they make their own outreach decisions directly. What distinguishes InvesTTable from generic startup databases is its scoring transparency. The platform shows five analytical layers for each evaluated startup, revealing how scores are calculated rather than presenting them as black boxes. Investors can adjust scoring criteria to match their own investment thesis, turning a generic benchmark into a personalized screening tool. Data freshness and status are disclosed alongside profiles, so investors know how current the information is. The feature set serves both sides' workflows. Investors access discovery tools, scoring systems, watchlists, and alerts to track interesting companies. Startups receive a free quality score highlighting their two most impactful improvements, along with visibility into percentile rankings and real investor interest signals. The founders are explicit about what the platform does not do: it neither brokers introductions nor manages deal pipelines. Every transaction happens off-platform between parties. The value proposition hinges on precision over volume. Rather than drowning in hundreds of unread applications, investors see fifty qualified profiles. Rather than scattering applications across networks, startups maintain one living profile. This specificity appeals to a particular operator: the independent scout who values structured signal and works on their own terms. InvesTTable's constraint is deliberate. By refusing to manage deals, handle funding rounds, or sit in the middle of transactions, it simplifies the product and keeps both investors and founders in control. That focus also means it does not replace existing deal-flow infrastructure for larger funds. The platform succeeds by being clear about what it is and what it is not, solving the matching problem without overreaching into deal management.
Fundraising-resources
S
Silvio Angelillo

Matching investors with the right startups has long been a friction point for both sides. Investors filter through dozens of unqualified leads, while founders pursue funds with misaligned theses, wasting everyone's time. InvesTTable tackles this discovery problem head-on by creating a dual-sided screening platform where investors find scored, benchmarked startups and founders build discoverable profiles that reach aligned capital. The platform's architecture reflects deliberate design choices. Rather than positioning itself as deal-flow software or an investment platform, InvesTTable focuses narrowly on discovery and screening. Founders control their own profiles completely, deciding what to share down to full stealth mode. Every company listing undergoes review for completeness and legitimacy before publication, addressing a core trust issue in startup discovery. Investors receive structured data without gatekeeping; they make their own outreach decisions directly. What distinguishes InvesTTable from generic startup databases is its scoring transparency. The platform shows five analytical layers for each evaluated startup, revealing how scores are calculated rather than presenting them as black boxes. Investors can adjust scoring criteria to match their own investment thesis, turning a generic benchmark into a personalized screening tool. Data freshness and status are disclosed alongside profiles, so investors know how current the information is. The feature set serves both sides' workflows. Investors access discovery tools, scoring systems, watchlists, and alerts to track interesting companies. Startups receive a free quality score highlighting their two most impactful improvements, along with visibility into percentile rankings and real investor interest signals. The founders are explicit about what the platform does not do: it neither brokers introductions nor manages deal pipelines. Every transaction happens off-platform between parties. The value proposition hinges on precision over volume. Rather than drowning in hundreds of unread applications, investors see fifty qualified profiles. Rather than scattering applications across networks, startups maintain one living profile. This specificity appeals to a particular operator: the independent scout who values structured signal and works on their own terms. InvesTTable's constraint is deliberate. By refusing to manage deals, handle funding rounds, or sit in the middle of transactions, it simplifies the product and keeps both investors and founders in control. That focus also means it does not replace existing deal-flow infrastructure for larger funds. The platform succeeds by being clear about what it is and what it is not, solving the matching problem without overreaching into deal management.

InvesTTable preview

Key features

  • Dual-Sided Screening: Connects investors with scored, benchmarked startups and founders with aligned capital sources.
  • Transparent Scoring System: Shows five analytical layers revealing exactly how startup scores are calculated.
See full listing
CoolMeow

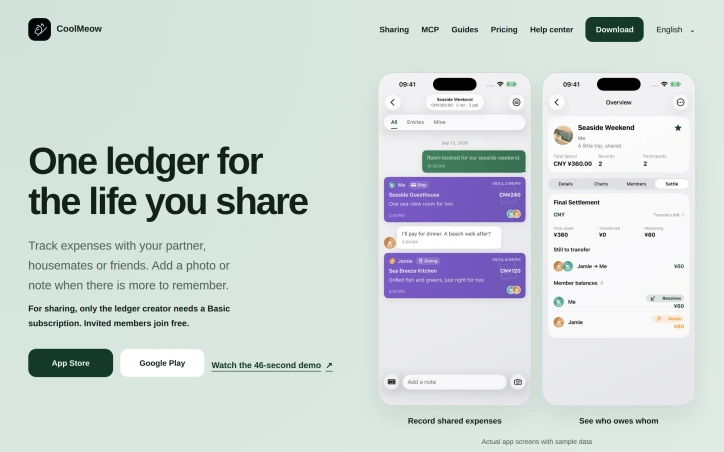
Dividing expenses among roommates, travel companions, or romantic partners remains one of those friction points that modern apps haven't fully resolved. CoolMeow addresses this gap by packaging expense tracking, photo attachment, and settlement calculations into a single ledger that syncs across iOS and Android. The product targets groups that need ongoing financial accounting: couples managing household costs, friend groups splitting trips, or roommates tracking shared utilities and groceries. The core functionality is straightforward—users log expenses, assign who paid and who benefited, and the app calculates resulting balances. Where it distinguishes itself from basic expense splitters is the attention to supporting context. Expenses can include photos and notes, keeping receipts and justifications alongside transactions rather than scattered across email or messaging apps. Several features demonstrate thoughtful design. Receipt scanning extracts amounts, merchants, dates, and times directly from photos, returning a draft for verification before commitment. Spending reports break down costs by date, category, and individual, with each total linking back to underlying transactions. Support for multiple currencies within a single ledger addresses the friction of international trips or cross-border payments, converting everything to a primary currency for settlement calculations. The architecture acknowledges payment logistics: CoolMeow calculates who owes whom but leaves actual transfers outside the app, avoiding the complexity and regulation of processing payments directly. One practical element is governance—the ledger creator controls who can add or view expenses and what role participants play. The business model reflects this philosophy. Personal expense tracking is free. Sharing requires the creator to hold an active Basic subscription, though invited participants join without paying. Receipt scanning also requires a subscription and carries usage limits. Cloud synchronization and ledger restoration similarly depend on an active subscription. This creates clear monetization while lowering initial friction for new users exploring the product. A notable addition is MCP support, allowing AI tools to query ledgers, check splits, and preview changes. This positions CoolMeow at the intersection of expense tracking and AI integration, though it currently applies only to cloud ledgers and requires separate AI service subscriptions.
Budgeting-apps
L
leconio

Dividing expenses among roommates, travel companions, or romantic partners remains one of those friction points that modern apps haven't fully resolved. CoolMeow addresses this gap by packaging expense tracking, photo attachment, and settlement calculations into a single ledger that syncs across iOS and Android. The product targets groups that need ongoing financial accounting: couples managing household costs, friend groups splitting trips, or roommates tracking shared utilities and groceries. The core functionality is straightforward—users log expenses, assign who paid and who benefited, and the app calculates resulting balances. Where it distinguishes itself from basic expense splitters is the attention to supporting context. Expenses can include photos and notes, keeping receipts and justifications alongside transactions rather than scattered across email or messaging apps. Several features demonstrate thoughtful design. Receipt scanning extracts amounts, merchants, dates, and times directly from photos, returning a draft for verification before commitment. Spending reports break down costs by date, category, and individual, with each total linking back to underlying transactions. Support for multiple currencies within a single ledger addresses the friction of international trips or cross-border payments, converting everything to a primary currency for settlement calculations. The architecture acknowledges payment logistics: CoolMeow calculates who owes whom but leaves actual transfers outside the app, avoiding the complexity and regulation of processing payments directly. One practical element is governance—the ledger creator controls who can add or view expenses and what role participants play. The business model reflects this philosophy. Personal expense tracking is free. Sharing requires the creator to hold an active Basic subscription, though invited participants join without paying. Receipt scanning also requires a subscription and carries usage limits. Cloud synchronization and ledger restoration similarly depend on an active subscription. This creates clear monetization while lowering initial friction for new users exploring the product. A notable addition is MCP support, allowing AI tools to query ledgers, check splits, and preview changes. This positions CoolMeow at the intersection of expense tracking and AI integration, though it currently applies only to cloud ledgers and requires separate AI service subscriptions.

CoolMeow preview

Key features

  • Expense Tracking: Users log expenses and assign who paid and who benefited with automatic settlement calculations
  • Receipt Scanning: Extracts amounts, merchants, dates, and times directly from photos with draft verification
See full listing
Invoala

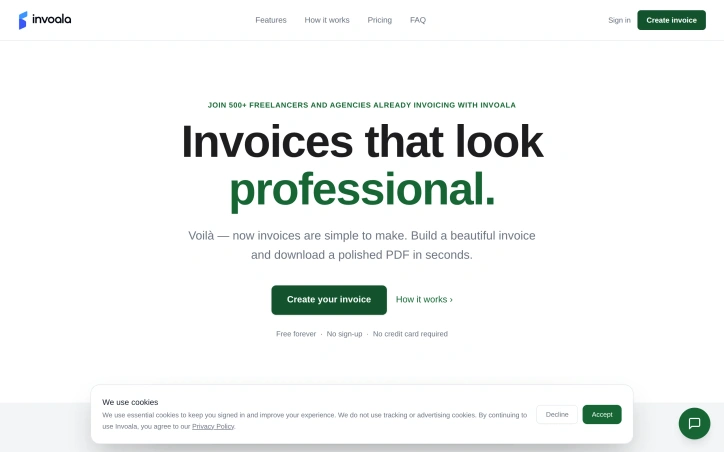
Freelancers squander time and money on invoice management, transforming what should be a simple administrative task into a recurring friction point. Invoala addresses this directly with a free invoice generator that combines professional PDF output, payment processing, and client management in a single interface. The product removes friction at every turn. The setup requires no account creation, no credit card, and no paywall. Freelancers describe their work in plain language and let AI complete the invoice with correct totals, or manually fill in details that the system saves for future use. The resulting PDFs are polished and brandable, generating professional-looking documents in seconds rather than minutes. Beyond document generation, Invoala bundles features that most freelancers assemble from multiple tools. A payment button on each invoice lets clients pay directly via card, Apple Pay, or Google Pay without leaving the document. The dashboard tracks which invoices remain open, which are due, and which are overdue, giving freelancers a clear view of cash flow. Client records persist across invoices so context doesn't get lost. Reusable service templates eliminate repetitive data entry for retainers and recurring line items. Tax rates and discount calculations happen automatically, avoiding manual arithmetic errors. Team workspaces allow agencies to collaborate and share client relationships. The sharing model stands out. Rather than sending static PDFs, freelancers can generate live share links that display real-time payment status, letting clients see at a glance whether an invoice has been settled. This transparency likely accelerates payments. The business model remains unencumbered. The tool is free forever with no sign-up friction, suggesting a play toward ubiquity and eventual monetization through payment processing fees or higher-tier features. Nothing in the public materials suggests hidden costs or upselling mechanics. User feedback clusters around simplicity and focus. Reviewers note the uncluttered interface and appreciate the decision to build a single, well-executed tool rather than a bloated bundle. For freelancers tired of juggling spreadsheets and email reminders, Invoala eliminates the overhead around invoicing while keeping money flowing in.
Invoicing-tools
A
Ashir Saminu

Freelancers squander time and money on invoice management, transforming what should be a simple administrative task into a recurring friction point. Invoala addresses this directly with a free invoice generator that combines professional PDF output, payment processing, and client management in a single interface. The product removes friction at every turn. The setup requires no account creation, no credit card, and no paywall. Freelancers describe their work in plain language and let AI complete the invoice with correct totals, or manually fill in details that the system saves for future use. The resulting PDFs are polished and brandable, generating professional-looking documents in seconds rather than minutes. Beyond document generation, Invoala bundles features that most freelancers assemble from multiple tools. A payment button on each invoice lets clients pay directly via card, Apple Pay, or Google Pay without leaving the document. The dashboard tracks which invoices remain open, which are due, and which are overdue, giving freelancers a clear view of cash flow. Client records persist across invoices so context doesn't get lost. Reusable service templates eliminate repetitive data entry for retainers and recurring line items. Tax rates and discount calculations happen automatically, avoiding manual arithmetic errors. Team workspaces allow agencies to collaborate and share client relationships. The sharing model stands out. Rather than sending static PDFs, freelancers can generate live share links that display real-time payment status, letting clients see at a glance whether an invoice has been settled. This transparency likely accelerates payments. The business model remains unencumbered. The tool is free forever with no sign-up friction, suggesting a play toward ubiquity and eventual monetization through payment processing fees or higher-tier features. Nothing in the public materials suggests hidden costs or upselling mechanics. User feedback clusters around simplicity and focus. Reviewers note the uncluttered interface and appreciate the decision to build a single, well-executed tool rather than a bloated bundle. For freelancers tired of juggling spreadsheets and email reminders, Invoala eliminates the overhead around invoicing while keeping money flowing in.

Invoala preview

Key features

  • AI Invoice Generation: Describe work in plain language and let AI complete the invoice with correct totals
  • Payment Processing: Direct payment buttons on invoices accepting card, Apple Pay, or Google Pay
See full listing
F

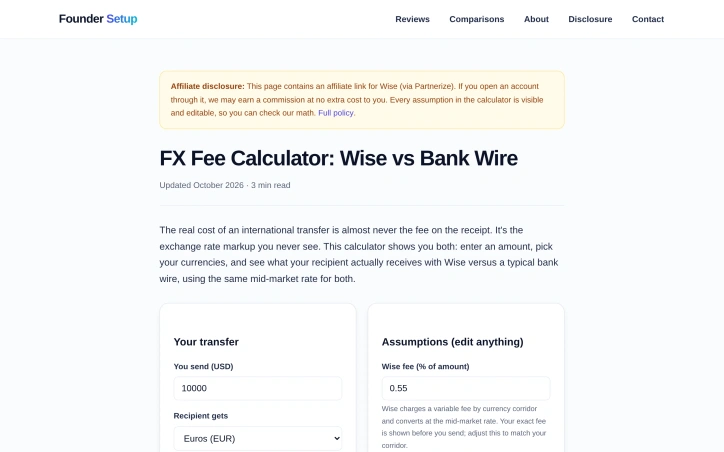
International money transfers hide their true cost. Banks advertise fees but bury exchange rate markups that often dwarf the stated charges, leaving senders and recipients both uncertain about real costs. This calculator addresses that opacity by letting users compare what they'll actually pay across multiple providers. The tool serves founders, freelancers, and anyone moving money across borders regularly. The core insight is sound: comparing providers requires accounting for both visible fees and invisible exchange rate spreads against a neutral benchmark. The calculator uses mid-market rates as that benchmark, then layers in each provider's markup to show total cost. The comparison focuses on Wise versus typical bank wires, with the interface accepting custom amounts and currency pairs. Users input a transfer amount, select source and destination currencies, and see what the recipient gets under each option. The calculator reveals the math behind each provider: Wise charges a percentage fee but converts at mid-market rates, while banks charge fixed wire fees but apply percentage markups to the exchange rate itself. On a 10,000 dollar transfer to Europe with a 3 percent bank markup, for example, the spread is 300 dollars versus a lower percentage fee from Wise. What distinguishes this tool is its transparency stance. Every assumption is editable, and the site invites users to adjust inputs to match their specific corridor and current rates. The calculator runs entirely in the browser without sending data to servers. The educational component also stands out: the copy explicitly explains why exchange rate markups matter more than headline fees, shifting founder focus away from advertised wire charges to the real cost lever. The site mentions that Wise's fee varies by corridor and can be higher or lower than assumed, and that large transfers or established bank relationships might negotiate better rates. It also references additional providers like Airwallex and UQPay for volume scenarios, implying broader comparison capabilities than the primary calculator displays. The free calculator carries an affiliate disclosure for Wise, creating a revenue model through commission on account openings, though this aligns with the tool's positioning rather than conflicting with it. For founders evaluating transfer options before committing capital abroad, the tool cuts through marketing language and presents the actual cost comparison. It works best for recurring transfers where the transparent fee model appeals to users comfortable with variable costs in exchange for rate certainty.
Money-transfer
F
Founder Setup

International money transfers hide their true cost. Banks advertise fees but bury exchange rate markups that often dwarf the stated charges, leaving senders and recipients both uncertain about real costs. This calculator addresses that opacity by letting users compare what they'll actually pay across multiple providers. The tool serves founders, freelancers, and anyone moving money across borders regularly. The core insight is sound: comparing providers requires accounting for both visible fees and invisible exchange rate spreads against a neutral benchmark. The calculator uses mid-market rates as that benchmark, then layers in each provider's markup to show total cost. The comparison focuses on Wise versus typical bank wires, with the interface accepting custom amounts and currency pairs. Users input a transfer amount, select source and destination currencies, and see what the recipient gets under each option. The calculator reveals the math behind each provider: Wise charges a percentage fee but converts at mid-market rates, while banks charge fixed wire fees but apply percentage markups to the exchange rate itself. On a 10,000 dollar transfer to Europe with a 3 percent bank markup, for example, the spread is 300 dollars versus a lower percentage fee from Wise. What distinguishes this tool is its transparency stance. Every assumption is editable, and the site invites users to adjust inputs to match their specific corridor and current rates. The calculator runs entirely in the browser without sending data to servers. The educational component also stands out: the copy explicitly explains why exchange rate markups matter more than headline fees, shifting founder focus away from advertised wire charges to the real cost lever. The site mentions that Wise's fee varies by corridor and can be higher or lower than assumed, and that large transfers or established bank relationships might negotiate better rates. It also references additional providers like Airwallex and UQPay for volume scenarios, implying broader comparison capabilities than the primary calculator displays. The free calculator carries an affiliate disclosure for Wise, creating a revenue model through commission on account openings, though this aligns with the tool's positioning rather than conflicting with it. For founders evaluating transfer options before committing capital abroad, the tool cuts through marketing language and presents the actual cost comparison. It works best for recurring transfers where the transparent fee model appeals to users comfortable with variable costs in exchange for rate certainty.

FX Fee Calculator preview
F

Key features

  • Multi-Provider Comparison: Compare transfer costs across different payment providers like Wise and banks
  • Mid-Market Rate Benchmark: Uses neutral mid-market exchange rates as a baseline for calculating true costs
See full listing
Quotelyo

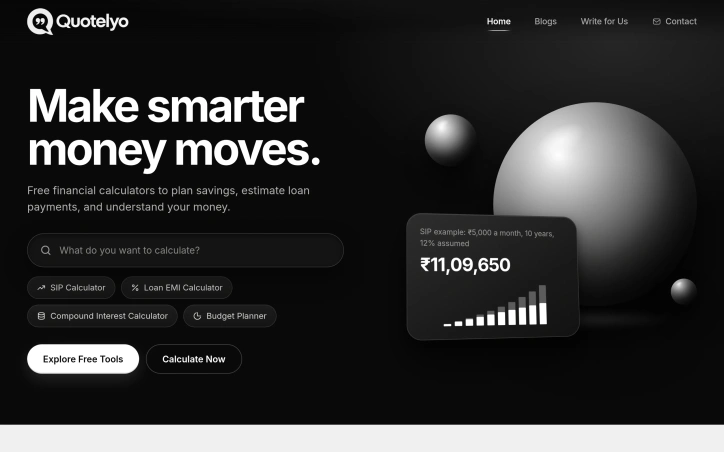
In an era where most financial tools demand personal data before offering basic calculations, Quotelyo takes a refreshingly different approach. The service addresses a genuine friction point for users seeking quick financial estimates without the privacy cost of registration, data collection, or cloud-dependent infrastructure. The product consists of eight calculators covering common personal finance scenarios—SIP returns, loan payments, and savings goal planning among them. All computation happens locally within the browser, meaning users avoid transmitting sensitive financial information to external servers or leaving traces of their calculations. What distinguishes Quotelyo is its deliberate simplicity paired with transparency. Rather than hiding the mechanics behind a black box, each calculator explicitly displays the formula it uses and states the assumptions embedded in the calculation. This approach builds trust and allows users to verify accuracy themselves. The tool supports custom interest rates, returns, and inflation figures, accommodating regional differences without requiring account creation or sign-up processes. The interface prioritizes speed and usability. Users select a calculator, enter their figures, and see results update instantly. Amounts can be displayed in any currency format the user selects, though this is purely presentational—no currency conversions occur automatically. The default values provided are explicitly labeled as examples rather than live market data, placing responsibility on users to supply their own figures from their financial institutions. The product's positioning reflects a clear philosophy: financial planning tools should empower users to make informed decisions based on accurate, verifiable math. By eliminating servers, tracking, and mandatory registration, Quotelyo removes barriers that traditionally gate such tools behind freemium models or data collection schemes. Quotelyo's distribution strategy includes listings across multiple discovery platforms including AgentWise, LaunchListed, and DevTool.io, signaling efforts to reach both general users and technical audiences. The lack of pricing information visible suggests a purely free model, though sustainability details remain undisclosed. The service works well for users who need occasional financial estimates and place high value on privacy, but its effectiveness depends entirely on users supplying accurate input data—the tool itself makes no claims about real-time rate accuracy or market conditions. For individuals tired of financial software that treats data collection as the primary product, Quotelyo offers a straightforward alternative focused on calculation rather than engagement metrics.
Financial-planning
K
Krish

In an era where most financial tools demand personal data before offering basic calculations, Quotelyo takes a refreshingly different approach. The service addresses a genuine friction point for users seeking quick financial estimates without the privacy cost of registration, data collection, or cloud-dependent infrastructure. The product consists of eight calculators covering common personal finance scenarios—SIP returns, loan payments, and savings goal planning among them. All computation happens locally within the browser, meaning users avoid transmitting sensitive financial information to external servers or leaving traces of their calculations. What distinguishes Quotelyo is its deliberate simplicity paired with transparency. Rather than hiding the mechanics behind a black box, each calculator explicitly displays the formula it uses and states the assumptions embedded in the calculation. This approach builds trust and allows users to verify accuracy themselves. The tool supports custom interest rates, returns, and inflation figures, accommodating regional differences without requiring account creation or sign-up processes. The interface prioritizes speed and usability. Users select a calculator, enter their figures, and see results update instantly. Amounts can be displayed in any currency format the user selects, though this is purely presentational—no currency conversions occur automatically. The default values provided are explicitly labeled as examples rather than live market data, placing responsibility on users to supply their own figures from their financial institutions. The product's positioning reflects a clear philosophy: financial planning tools should empower users to make informed decisions based on accurate, verifiable math. By eliminating servers, tracking, and mandatory registration, Quotelyo removes barriers that traditionally gate such tools behind freemium models or data collection schemes. Quotelyo's distribution strategy includes listings across multiple discovery platforms including AgentWise, LaunchListed, and DevTool.io, signaling efforts to reach both general users and technical audiences. The lack of pricing information visible suggests a purely free model, though sustainability details remain undisclosed. The service works well for users who need occasional financial estimates and place high value on privacy, but its effectiveness depends entirely on users supplying accurate input data—the tool itself makes no claims about real-time rate accuracy or market conditions. For individuals tired of financial software that treats data collection as the primary product, Quotelyo offers a straightforward alternative focused on calculation rather than engagement metrics.

Quotelyo preview

Key features

  • Browser-Based Calculation: All computation happens locally in the browser without transmitting financial data to external servers
  • Formula Transparency: Each calculator displays its formula and the assumptions embedded in the calculation for user verification
See full listing
QuickEstimators

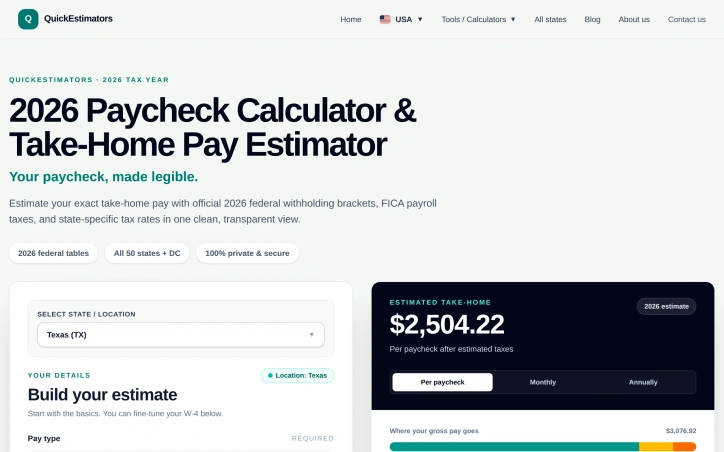
Calculating take-home pay remains a frustrating gap in financial planning for most workers. Employees know their gross salary, but navigating federal withholding tables, FICA calculations, and state-specific tax rules to arrive at an actual paycheck amount requires either specialized knowledge or guesswork. QuickEstimators fills this gap with a straightforward paycheck calculator built around 2026 tax figures. The platform targets employees, freelancers, and professionals who need to understand their net earnings for budgeting, career decisions, or financial planning. The founder describes the problem directly: workers struggle with changing federal brackets, Social Security and Medicare taxes, and the complexity of multi-state tax treatment. QuickEstimators promises fast, transparent calculations covering all 50 states plus D.C., using the latest federal withholding methodology from IRS Publication 15-T. The core experience is clean and methodical. Users input gross pay, frequency, filing status, and location, then refine details like W-4 adjustments, dependent credits, and pre-tax deductions (401(k), health insurance, HSA contributions). The calculator immediately breaks down where each dollar goes: federal income tax, Social Security, Medicare, state tax, and post-tax deductions. A sample Texas estimate shows the math in detail, making the withholding process legible rather than opaque. Several design choices stand out. The calculator handles multi-job scenarios through Step 2 withholding guidance, a detail that matters for married couples and gig workers. The product emphasizes privacy by storing no salary data and maintaining CCPA compliance. Users can download PDF summaries of estimates or embed the calculator on other sites, expanding utility beyond a standalone tool. The state tax engine deserves mention. Tax treatment varies wildly across jurisdictions: graduated rates, flat rates, and states with no income tax. Building this engine correctly requires state-specific logic, and the product claims full 50-state coverage with IRS compliance. Whether that translates to accuracy in edge cases isn't evident from marketing copy alone, but the claim is credible. The product offers no subscription model or premium tier; it functions as a free calculator. This approach makes sense for a financial transparency tool competing partly on accessibility and trust. Revenue model details are absent, but the business likely monetizes through affiliate relationships with payroll or financial planning services, or through embeds on employer websites. QuickEstimators solves a real problem with directness and attention to tax law detail. For anyone uncertain about paycheck math, it beats spreadsheets or mental math.
Payroll-software
M
Muhammad Tahir

Calculating take-home pay remains a frustrating gap in financial planning for most workers. Employees know their gross salary, but navigating federal withholding tables, FICA calculations, and state-specific tax rules to arrive at an actual paycheck amount requires either specialized knowledge or guesswork. QuickEstimators fills this gap with a straightforward paycheck calculator built around 2026 tax figures. The platform targets employees, freelancers, and professionals who need to understand their net earnings for budgeting, career decisions, or financial planning. The founder describes the problem directly: workers struggle with changing federal brackets, Social Security and Medicare taxes, and the complexity of multi-state tax treatment. QuickEstimators promises fast, transparent calculations covering all 50 states plus D.C., using the latest federal withholding methodology from IRS Publication 15-T. The core experience is clean and methodical. Users input gross pay, frequency, filing status, and location, then refine details like W-4 adjustments, dependent credits, and pre-tax deductions (401(k), health insurance, HSA contributions). The calculator immediately breaks down where each dollar goes: federal income tax, Social Security, Medicare, state tax, and post-tax deductions. A sample Texas estimate shows the math in detail, making the withholding process legible rather than opaque. Several design choices stand out. The calculator handles multi-job scenarios through Step 2 withholding guidance, a detail that matters for married couples and gig workers. The product emphasizes privacy by storing no salary data and maintaining CCPA compliance. Users can download PDF summaries of estimates or embed the calculator on other sites, expanding utility beyond a standalone tool. The state tax engine deserves mention. Tax treatment varies wildly across jurisdictions: graduated rates, flat rates, and states with no income tax. Building this engine correctly requires state-specific logic, and the product claims full 50-state coverage with IRS compliance. Whether that translates to accuracy in edge cases isn't evident from marketing copy alone, but the claim is credible. The product offers no subscription model or premium tier; it functions as a free calculator. This approach makes sense for a financial transparency tool competing partly on accessibility and trust. Revenue model details are absent, but the business likely monetizes through affiliate relationships with payroll or financial planning services, or through embeds on employer websites. QuickEstimators solves a real problem with directness and attention to tax law detail. For anyone uncertain about paycheck math, it beats spreadsheets or mental math.

QuickEstimators preview

Key features

  • Paycheck Calculator: Computes net take-home pay by processing gross salary against federal, state, and local tax rules.
  • Tax Breakdown Visualization: Displays itemized breakdown showing federal income tax, Social Security, Medicare, state tax, and deductions.
See full listing
NeevHR

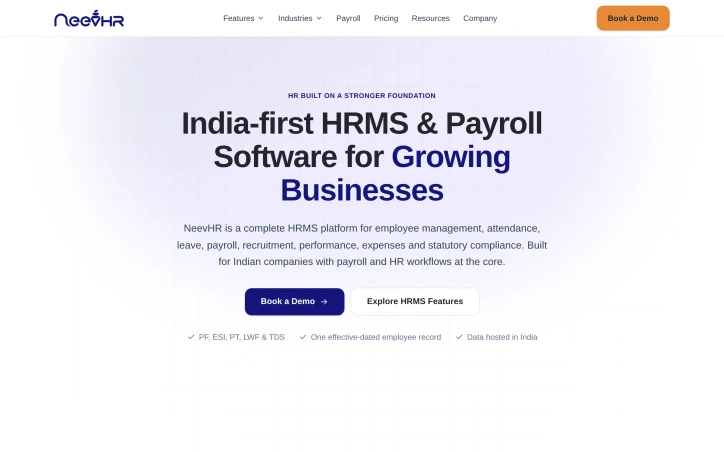
Implementing payroll and HR systems in India presents unique challenges around statutory compliance, regulatory changes, and localized workflows. NeevHR addresses this complexity by building a purpose-built platform for Indian companies that centralizes employee management, payroll processing, and statutory compliance in a single system designed from the ground up for Indian business requirements. The platform manages the complete employee lifecycle from recruitment through exit, connecting hiring, onboarding, attendance tracking, shift rostering, leave management, payroll processing, performance reviews, expense management, and final settlement. What distinguishes NeevHR from generic HR platforms is its India-specific foundation. Rather than treating compliance as an afterthought, statutory requirements like Employee Provident Fund contributions, ESI deductions, professional tax, TDS, LWF calculations, and gratuity provisions are embedded into the core workflows. The system also accounts for regulations specific to Indian employment like POSH compliance and the DPDP Act 2023. A defining feature is the effective-dated employee record that maintains historical accuracy across organizational changes. This single record flows through all HR functions, eliminating data silos. HR administrators can configure leave rules, attendance policies, payroll structures, and appraisal processes through the platform's interface without requiring code or external consulting, which reduces implementation timelines to four to eight weeks compared to six to twelve months for traditional deployments. The platform includes a mobile application that extends self-service capabilities to employees for accessing payslips, submitting leave requests, tracking attendance, and approving workflows. Data residency within India addresses data sovereignty concerns for companies managing sensitive employee information. The dashboard provides visibility into key workforce metrics including headcount trends, attrition by department, recruitment pipeline status, and payroll status. The platform targets growing Indian businesses that operate at sufficient scale to justify dedicated HR infrastructure but seek simpler deployment and configuration than enterprise-grade competitors. The depth of statutory compliance coverage and no-code configurability for HR teams positions NeevHR as a practical alternative to either manual spreadsheet processes or lengthy enterprise implementations. Free HR calculation tools available through the platform provide additional value for businesses evaluating HR and payroll decisions.
Payroll-software
N
NeevHR

Implementing payroll and HR systems in India presents unique challenges around statutory compliance, regulatory changes, and localized workflows. NeevHR addresses this complexity by building a purpose-built platform for Indian companies that centralizes employee management, payroll processing, and statutory compliance in a single system designed from the ground up for Indian business requirements. The platform manages the complete employee lifecycle from recruitment through exit, connecting hiring, onboarding, attendance tracking, shift rostering, leave management, payroll processing, performance reviews, expense management, and final settlement. What distinguishes NeevHR from generic HR platforms is its India-specific foundation. Rather than treating compliance as an afterthought, statutory requirements like Employee Provident Fund contributions, ESI deductions, professional tax, TDS, LWF calculations, and gratuity provisions are embedded into the core workflows. The system also accounts for regulations specific to Indian employment like POSH compliance and the DPDP Act 2023. A defining feature is the effective-dated employee record that maintains historical accuracy across organizational changes. This single record flows through all HR functions, eliminating data silos. HR administrators can configure leave rules, attendance policies, payroll structures, and appraisal processes through the platform's interface without requiring code or external consulting, which reduces implementation timelines to four to eight weeks compared to six to twelve months for traditional deployments. The platform includes a mobile application that extends self-service capabilities to employees for accessing payslips, submitting leave requests, tracking attendance, and approving workflows. Data residency within India addresses data sovereignty concerns for companies managing sensitive employee information. The dashboard provides visibility into key workforce metrics including headcount trends, attrition by department, recruitment pipeline status, and payroll status. The platform targets growing Indian businesses that operate at sufficient scale to justify dedicated HR infrastructure but seek simpler deployment and configuration than enterprise-grade competitors. The depth of statutory compliance coverage and no-code configurability for HR teams positions NeevHR as a practical alternative to either manual spreadsheet processes or lengthy enterprise implementations. Free HR calculation tools available through the platform provide additional value for businesses evaluating HR and payroll decisions.

NeevHR preview

Key features

  • Unified Employee Lifecycle Management: Manages the complete employee journey from recruitment through exit, including hiring, onboarding, attendance, leave management, payroll, and performance reviews.
  • India-Specific Statutory Compliance: Embeds PF, ESI, professional tax, TDS, LWF calculations, and gratuity provisions into core workflows with POSH and DPDP Act 2023 support.
See full listing
MoneyFlow: No bank login

Most budgeting apps promise to simplify your finances by connecting to your bank, then promptly frustrate you with failed syncs, security concerns, and endless transaction categorization. MoneyFlow takes the opposite approach entirely. Rather than chasing bank connectivity as a requirement, it treats manual entry as a feature, positioning itself for users who value privacy, simplicity, and control over the false promise of frictionless automation. The core tension the app addresses is real: people end each month with no savings despite earning enough money, not because they lack income but because they cannot clearly see where their money actually goes. MoneyFlow answers this through a deliberate constraint. By requiring users to log transactions manually, it forces intentionality without the bloat that plagues competing products. The app then calculates a single number designed to answer the most practical question users face: how much can I safely spend right now after accounting for bills, debts, subscriptions, and goals? The product organizes finances into seven distinct categories that cover the major ways money moves through a person's life. Beyond basic spending tracking, it handles goals with deadlines, tracks investments across stocks and crypto by total contributed amount rather than market value, monitors debt payoff dates with precise math, alerts users before subscription renewals, logs variable bills separately from fixed ones, and consolidates income in one place. This modular approach avoids the false comprehensiveness that leaves users more confused than when they started. What distinguishes MoneyFlow philosophically is honesty about its constraints. The app does not pretend manual tracking is as effortless as bank sync; it argues the tradeoff is worth it. No broken connections mean no wasted time troubleshooting, no reconciliation required, no surprise duplicates. Data stays on the user's device. The feature set itself is clean and uncluttered, with no ads and no paywall on core tools. The business model depends on Pro subscribers, not user attention, which aligns incentives toward genuine product utility rather than engagement metrics. The app positions itself for a specific user: someone who prioritizes control and clarity over perceived convenience, who doesn't trust banks to handle their financial data safely, and who can sustain a habit of logging their own spending. For that audience, MoneyFlow offers something increasingly rare in this category—a tool designed to be simpler than reality rather than more complicated.
Financial-planning
E
EL BEQQAL YOUSSEF

Most budgeting apps promise to simplify your finances by connecting to your bank, then promptly frustrate you with failed syncs, security concerns, and endless transaction categorization. MoneyFlow takes the opposite approach entirely. Rather than chasing bank connectivity as a requirement, it treats manual entry as a feature, positioning itself for users who value privacy, simplicity, and control over the false promise of frictionless automation. The core tension the app addresses is real: people end each month with no savings despite earning enough money, not because they lack income but because they cannot clearly see where their money actually goes. MoneyFlow answers this through a deliberate constraint. By requiring users to log transactions manually, it forces intentionality without the bloat that plagues competing products. The app then calculates a single number designed to answer the most practical question users face: how much can I safely spend right now after accounting for bills, debts, subscriptions, and goals? The product organizes finances into seven distinct categories that cover the major ways money moves through a person's life. Beyond basic spending tracking, it handles goals with deadlines, tracks investments across stocks and crypto by total contributed amount rather than market value, monitors debt payoff dates with precise math, alerts users before subscription renewals, logs variable bills separately from fixed ones, and consolidates income in one place. This modular approach avoids the false comprehensiveness that leaves users more confused than when they started. What distinguishes MoneyFlow philosophically is honesty about its constraints. The app does not pretend manual tracking is as effortless as bank sync; it argues the tradeoff is worth it. No broken connections mean no wasted time troubleshooting, no reconciliation required, no surprise duplicates. Data stays on the user's device. The feature set itself is clean and uncluttered, with no ads and no paywall on core tools. The business model depends on Pro subscribers, not user attention, which aligns incentives toward genuine product utility rather than engagement metrics. The app positions itself for a specific user: someone who prioritizes control and clarity over perceived convenience, who doesn't trust banks to handle their financial data safely, and who can sustain a habit of logging their own spending. For that audience, MoneyFlow offers something increasingly rare in this category—a tool designed to be simpler than reality rather than more complicated.

MoneyFlow: No bank login preview

Key features

  • Manual Transaction Logging: Users manually log spending to maintain intentionality and privacy while eliminating failed syncs
  • Spendable Amount Calculator: Calculates how much money can be safely spent after accounting for bills, debts, subscriptions, and goals
See full listing
B

Aluminum fabricators in India waste countless hours on manual calculations that should take minutes, a problem Barimap directly addresses. The software automates the tedious work of computing profile lengths, hardware quantities, and material requirements for window and door installations, then transforms those calculations into professional PDF quotations ready to share with clients. The standout differentiators lie in both practicality and accessibility. The app works completely offline, removing dependency on internet connectivity—critical for fabricators working on job sites or in areas with spotty service. Language support extends to Gujarati, Hindi, and English, making the tool genuinely accessible across India's diverse fabricator base rather than requiring English-only competency. Integration with WhatsApp for quotation delivery matches how these businesses already communicate with clients, reducing friction between measurement and close. Speed is another defining feature. The application promises conversion from project entry to branded, client-ready PDF quotation in under a minute. This efficiency compounds across a fabricator's day, reclaiming the 2-4 hours typically consumed by manual calculations. The software supports industry-standard specifications including 40mm, 60mm, and 65mm profiles alongside 2T, 3T, and 4T track systems, indicating thoughtful design informed by actual fabricator workflows. Beyond immediate calculations, the tool maintains searchable project history organized by client name or address. For repeat orders, retrieving and reusing past measurements eliminates re-entry and recalculation, translating saved time into recovered revenue from efficiently serving returning clients. The business model emphasizes low friction to trial. Users access one month free without providing a credit card, removing the hesitation many small business owners feel toward software adoption. This approach acknowledges that fabricators deciding between continuing their paper-based system and switching to software need meaningful time to experience the value proposition. Barimap targets a specific, underserved segment of India's manufacturing economy with a laser-focused solution. It does not attempt to become an all-in-one business platform; instead it concentrates entirely on the discrete problem that wastes the most time in a fabricator's day. For aluminum window businesses operating in India, the combination of offline capability, local languages, WhatsApp integration, and zero-entry cost positions the tool as a practical modernization path with minimal organizational disruption.
Invoicing-tools
P
PD

Aluminum fabricators in India waste countless hours on manual calculations that should take minutes, a problem Barimap directly addresses. The software automates the tedious work of computing profile lengths, hardware quantities, and material requirements for window and door installations, then transforms those calculations into professional PDF quotations ready to share with clients. The standout differentiators lie in both practicality and accessibility. The app works completely offline, removing dependency on internet connectivity—critical for fabricators working on job sites or in areas with spotty service. Language support extends to Gujarati, Hindi, and English, making the tool genuinely accessible across India's diverse fabricator base rather than requiring English-only competency. Integration with WhatsApp for quotation delivery matches how these businesses already communicate with clients, reducing friction between measurement and close. Speed is another defining feature. The application promises conversion from project entry to branded, client-ready PDF quotation in under a minute. This efficiency compounds across a fabricator's day, reclaiming the 2-4 hours typically consumed by manual calculations. The software supports industry-standard specifications including 40mm, 60mm, and 65mm profiles alongside 2T, 3T, and 4T track systems, indicating thoughtful design informed by actual fabricator workflows. Beyond immediate calculations, the tool maintains searchable project history organized by client name or address. For repeat orders, retrieving and reusing past measurements eliminates re-entry and recalculation, translating saved time into recovered revenue from efficiently serving returning clients. The business model emphasizes low friction to trial. Users access one month free without providing a credit card, removing the hesitation many small business owners feel toward software adoption. This approach acknowledges that fabricators deciding between continuing their paper-based system and switching to software need meaningful time to experience the value proposition. Barimap targets a specific, underserved segment of India's manufacturing economy with a laser-focused solution. It does not attempt to become an all-in-one business platform; instead it concentrates entirely on the discrete problem that wastes the most time in a fabricator's day. For aluminum window businesses operating in India, the combination of offline capability, local languages, WhatsApp integration, and zero-entry cost positions the tool as a practical modernization path with minimal organizational disruption.

Barimap preview
B

Key features

  • Offline Functionality: The application works completely offline, removing dependency on internet connectivity for job site operations.
  • Multilingual Support: Supports Gujarati, Hindi, and English to serve India's diverse fabricator base without requiring English-only competency.
See full listing
Cove

Personal finance management remains fragmented across multiple apps and bank websites, leaving most people unable to answer basic questions about their spending patterns or financial health. Cove addresses this fragmentation by consolidating banking, investments, credit cards, and subscriptions into a single dashboard while layering AI assistance on top. The product targets financially conscious individuals ranging from students to professionals who want oversight without the friction of manual spreadsheets or juggling separate logins. The core value proposition centers on visibility and action: see everything in one place, identify wasteful subscriptions, and get concrete guidance on spending and savings. Several capabilities distinguish Cove from basic aggregation tools. The AI assistant transforms financial data into conversational insights, letting users ask open-ended questions like "what do I spend on food?" rather than digging through transaction histories. This natural language interface lowers the barrier for people who find traditional budgeting tools tedious. The subscription detection feature specifically targets recurring charges, a known pain point where consumers often forget about free trials or low-cost services that accumulate. The platform's budgeting engine generates recommendations based on actual spending patterns rather than zero-based assumptions, which should improve adoption compared to traditional budgeting tools that feel prescriptive. Weekly money recaps keep users informed without requiring active engagement, addressing the information asymmetry most people face around their finances. Notably, Cove offers a bill negotiation service where the company's team contacts providers on users' behalf—a concierge element uncommon in fintech. This suggests a willingness to bundle services that deliver concrete value, like actual bill reductions, rather than stopping at pure visibility. On trust and security, Cove positions read-only connections prominently, meaning the app can't move money or initiate transactions. The company holds SOC 2 Type II certification and uses 256-bit encryption, standard practices that nonetheless matter when asking users to link sensitive financial accounts. App Store ratings of 4.4 and Google Play ratings of 4.6 suggest reasonable user satisfaction in the real world. The product notably avoids anchoring on what it doesn't do—there's no mention of investment advice, robo-advising, or lending products. This focused scope, combined with the emphasis on connectivity and AI-driven insights, positions Cove as a financial command center rather than a full wealth management platform. For users drowning in financial chaos, that clarity has appeal.
Budgeting-apps
A
Abhishek Sharma

Personal finance management remains fragmented across multiple apps and bank websites, leaving most people unable to answer basic questions about their spending patterns or financial health. Cove addresses this fragmentation by consolidating banking, investments, credit cards, and subscriptions into a single dashboard while layering AI assistance on top. The product targets financially conscious individuals ranging from students to professionals who want oversight without the friction of manual spreadsheets or juggling separate logins. The core value proposition centers on visibility and action: see everything in one place, identify wasteful subscriptions, and get concrete guidance on spending and savings. Several capabilities distinguish Cove from basic aggregation tools. The AI assistant transforms financial data into conversational insights, letting users ask open-ended questions like "what do I spend on food?" rather than digging through transaction histories. This natural language interface lowers the barrier for people who find traditional budgeting tools tedious. The subscription detection feature specifically targets recurring charges, a known pain point where consumers often forget about free trials or low-cost services that accumulate. The platform's budgeting engine generates recommendations based on actual spending patterns rather than zero-based assumptions, which should improve adoption compared to traditional budgeting tools that feel prescriptive. Weekly money recaps keep users informed without requiring active engagement, addressing the information asymmetry most people face around their finances. Notably, Cove offers a bill negotiation service where the company's team contacts providers on users' behalf—a concierge element uncommon in fintech. This suggests a willingness to bundle services that deliver concrete value, like actual bill reductions, rather than stopping at pure visibility. On trust and security, Cove positions read-only connections prominently, meaning the app can't move money or initiate transactions. The company holds SOC 2 Type II certification and uses 256-bit encryption, standard practices that nonetheless matter when asking users to link sensitive financial accounts. App Store ratings of 4.4 and Google Play ratings of 4.6 suggest reasonable user satisfaction in the real world. The product notably avoids anchoring on what it doesn't do—there's no mention of investment advice, robo-advising, or lending products. This focused scope, combined with the emphasis on connectivity and AI-driven insights, positions Cove as a financial command center rather than a full wealth management platform. For users drowning in financial chaos, that clarity has appeal.

Cove preview

Key features

  • Consolidated Dashboard: Aggregates banking, investments, credit cards, and subscriptions into a single interface
  • AI Financial Assistant: Answers open-ended questions about spending patterns through natural language conversation
See full listing
Arrel: Budget & Money

Personal finance apps have traded user privacy for free services for so long that Arrel's opposite approach feels almost radical. This iOS and iPad application inverts the typical business model: instead of harvesting spending data to fuel advertising or resale, it keeps everything offline and on your device, with no analytics tracking, no ads, and no third-party SDKs lurking in the background. The app targets people who want to manage their money without wondering if their financial details are being profited from elsewhere. You can use Arrel entirely without creating an account, though free sync across devices becomes available once you choose to sign in. The core product respects your autonomy at every level. Beyond privacy, Arrel handles the actual work of personal finance competently. It tracks multiple account types—cash, bank, savings, and credit cards—each in their own currency, which matters for anyone managing money across borders. The budgeting approach is particularly thoughtful, distinguishing between committed expenses and available money, so recurring bills like rent next week don't artificially inflate your spending budget for the month. Investment tracking extends beyond simple logging. You can build portfolios across stocks, ETFs, and crypto, and Arrel automatically calculates holdings and cost basis as you record buys and sells. Premium subscribers access live pricing for these assets; everyone else can input values manually. The app also calculates net worth, visualizes income versus expenses, and breaks down spending by category to surface spending patterns. The feature set feels complete without becoming overwhelming. Home Screen widgets and a read-only Apple Watch app keep essentials accessible. You can import bank statements from CSV and export all your data whenever you want, avoiding the lock-in that many finance apps rely on. Recent updates added Apple Intelligence features on supported devices for querying finances and categorizing imported transactions, processed entirely on-device. The business model is straightforward: the base app is free, and a premium subscription unlocks unlimited accounts, portfolios, budgets, trackers, analytics history, multi-currency exchange rates, shared trackers, PDF reports, and cash-flow forecasting. Sync and CSV export remain free regardless of subscription. Arrel succeeds because it solves a real problem—managing personal finances privately—without over-engineering the solution. It's a tool that trusts users rather than exploiting them.
Budgeting-apps
L
Luis

Personal finance apps have traded user privacy for free services for so long that Arrel's opposite approach feels almost radical. This iOS and iPad application inverts the typical business model: instead of harvesting spending data to fuel advertising or resale, it keeps everything offline and on your device, with no analytics tracking, no ads, and no third-party SDKs lurking in the background. The app targets people who want to manage their money without wondering if their financial details are being profited from elsewhere. You can use Arrel entirely without creating an account, though free sync across devices becomes available once you choose to sign in. The core product respects your autonomy at every level. Beyond privacy, Arrel handles the actual work of personal finance competently. It tracks multiple account types—cash, bank, savings, and credit cards—each in their own currency, which matters for anyone managing money across borders. The budgeting approach is particularly thoughtful, distinguishing between committed expenses and available money, so recurring bills like rent next week don't artificially inflate your spending budget for the month. Investment tracking extends beyond simple logging. You can build portfolios across stocks, ETFs, and crypto, and Arrel automatically calculates holdings and cost basis as you record buys and sells. Premium subscribers access live pricing for these assets; everyone else can input values manually. The app also calculates net worth, visualizes income versus expenses, and breaks down spending by category to surface spending patterns. The feature set feels complete without becoming overwhelming. Home Screen widgets and a read-only Apple Watch app keep essentials accessible. You can import bank statements from CSV and export all your data whenever you want, avoiding the lock-in that many finance apps rely on. Recent updates added Apple Intelligence features on supported devices for querying finances and categorizing imported transactions, processed entirely on-device. The business model is straightforward: the base app is free, and a premium subscription unlocks unlimited accounts, portfolios, budgets, trackers, analytics history, multi-currency exchange rates, shared trackers, PDF reports, and cash-flow forecasting. Sync and CSV export remain free regardless of subscription. Arrel succeeds because it solves a real problem—managing personal finances privately—without over-engineering the solution. It's a tool that trusts users rather than exploiting them.

Arrel: Budget & Money preview

Key features

  • Offline Privacy: All financial data stays on-device with no analytics tracking, ads, or third-party SDKs
  • Multi-Currency Support: Tracks cash, bank, savings, and credit cards each in separate currencies for international use
See full listing
AI Budget Assistant

Spreadsheet-based family budgets collapse under their own friction. AI Budget Assistant addresses this by automating the most tedious part of household finance management: data entry. Instead of typing receipts or forwarding bank statements, family members log expenses through voice commands or photos of receipts, which the AI then categorizes and summarizes. The result is a shared, real-time budget visible to everyone in the household. The product solves a specific pain point: families struggling to coordinate on spending because the process of tracking expenses is too burdensome to maintain consistently. The target audience is households where multiple people contribute expenses but lack a centralized, frictionless way to see them together. It appeals to people who find spreadsheets tedious and prefer input methods that don't require typing. Several capabilities distinguish AI Budget Assistant from basic expense-tracking apps. Receipt scanning uses optical character recognition to extract line items, amounts, and merchant names from photos rather than forcing manual entry. Voice input allows users to log expenses conversationally. The platform supports shared access across family members, with all participants seeing the same data in real-time across phones, tablets, and web browsers. Beyond tracking, it includes budget creation, savings goal management, debt monitoring, and expense analytics broken down by category and merchant. Bank integration imports transactions directly from Wise and other institutions via CSV or PDF, with duplicate detection to prevent double-counting. The AI component extends beyond data entry into analysis. Instead of reading charts, users can ask natural-language questions about their finances and receive conversational responses. This positions the product as more of a financial advisor interface than a simple ledger. The business model relies on a freemium structure. Core features are free, while a Pro plan removes limits on AI queries and enables advanced analytics. The company does not disclose specific pricing or feature breakdowns beyond this split. For households tired of juggling multiple tools or spreadsheet disciplines, AI Budget Assistant offers a more human-friendly approach to a fundamentally important problem. Its strength lies not in novelty but in consolidating scattered household finance management into a single, voice-and-photo-driven interface designed for collaboration rather than isolation.
Spreadsheet-based family budgets collapse under their own friction. AI Budget Assistant addresses this by automating the most tedious part of household finance management: data entry. Instead of typing receipts or forwarding bank statements, family members log expenses through voice commands or photos of receipts, which the AI then categorizes and summarizes. The result is a shared, real-time budget visible to everyone in the household. The product solves a specific pain point: families struggling to coordinate on spending because the process of tracking expenses is too burdensome to maintain consistently. The target audience is households where multiple people contribute expenses but lack a centralized, frictionless way to see them together. It appeals to people who find spreadsheets tedious and prefer input methods that don't require typing. Several capabilities distinguish AI Budget Assistant from basic expense-tracking apps. Receipt scanning uses optical character recognition to extract line items, amounts, and merchant names from photos rather than forcing manual entry. Voice input allows users to log expenses conversationally. The platform supports shared access across family members, with all participants seeing the same data in real-time across phones, tablets, and web browsers. Beyond tracking, it includes budget creation, savings goal management, debt monitoring, and expense analytics broken down by category and merchant. Bank integration imports transactions directly from Wise and other institutions via CSV or PDF, with duplicate detection to prevent double-counting. The AI component extends beyond data entry into analysis. Instead of reading charts, users can ask natural-language questions about their finances and receive conversational responses. This positions the product as more of a financial advisor interface than a simple ledger. The business model relies on a freemium structure. Core features are free, while a Pro plan removes limits on AI queries and enables advanced analytics. The company does not disclose specific pricing or feature breakdowns beyond this split. For households tired of juggling multiple tools or spreadsheet disciplines, AI Budget Assistant offers a more human-friendly approach to a fundamentally important problem. Its strength lies not in novelty but in consolidating scattered household finance management into a single, voice-and-photo-driven interface designed for collaboration rather than isolation.

AI Budget Assistant preview

Key features

  • Receipt Scanning: Extracts line items, amounts, and merchant names from photos using optical character recognition.
  • Voice Logging: Allows users to log expenses conversationally without typing.
See full listing